
This interview was originally published in De La Rue’s Going Beyond newsletter, October 2026 edition. Republished with thanks to De La Rue.
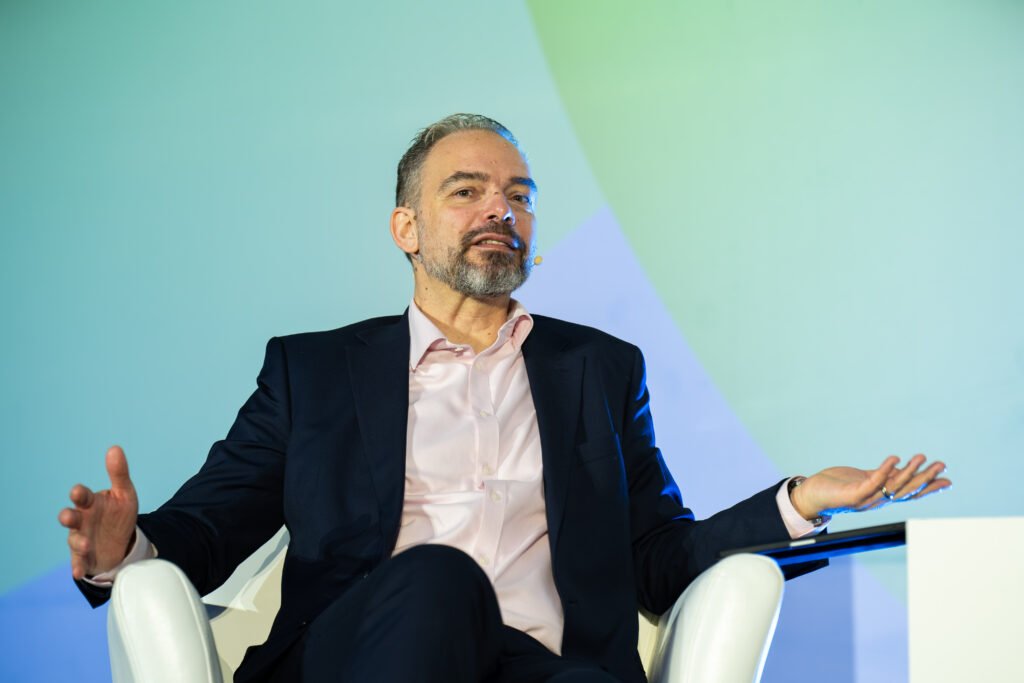
As Director General of the International Currency Association (ICA), Frane Maroević is a leading advocate for the global currency industry and the continued role of cash. In this interview, he discusses the ICA’s priorities, its latest research project, and why protecting access to physical currency remains critical for national infrastructure and sovereignty globally.
In your role as Director General of the International Currency Association, what is your main focus, and what do you want the ICA to achieve?
My first priority is to support our members. The ICA unites the global currency industry with a single voice, connecting innovators, thought leaders, and businesses across design, production, security and distribution of banknotes and coins. Our mission is also to highlight the ongoing importance of cash and to shape the future of payments, and we do this through collaboration, research, and advocacy.
Recognising this effort and commitment to the industry, in the last 12 months we welcomed 14 new members, growing from 22 to 36 members, most notably through a merger with the International Mint Industry Association in January 2026. This was an important move to join forces and work together to strengthen the industry for the benefit of companies involved in both banknotes and coins.
Our priorities are: first, effective advocacy, so that legislation such as the EU Single Currency Package genuinely protects access to and acceptance of cash. Second, credible evidence, through independent research such as our Value of Cash study, so that the debate about the future of payments is based on facts rather than assumptions. Third, better public understanding, through our Cash Matters campaign, that cash is a public good which concerns everyone, not just our industry. Fourth, progress on shared industry challenges, above all environmental protection and sustainability, by developing common principles and practices, and by sharing approaches and data. And finally, building a strong community across this vibrant industry, because we achieve more together than any company can alone.
I am very grateful for the support I receive in this role, above all from our very active board members, each engaged in different initiatives, some of whom also provide additional support and advice through their companies.
You mentioned the Value of Cash study. Please can you tell us a bit more about the process followed, your findings, and why these findings are important for central banks?
We all understand the benefits of cash and can talk about its role in protecting our sovereignty, national security, resilience, privacy, and inclusion. Yet when it comes to taking decisions about cash, the only figures available so far have been costs: the cost of production, of transport, of handling. This is where this study comes in. It fills an important gap in the cost-benefit analysis of cash and its role in our societies.
This task was enthusiastically taken up by Professor Julia Pitters, Professor and Head of the Distance Learning Program in Business Psychology at International University of Applied Sciences, and Professor Franz Seitz, Professor of Economics at Weiden Technical University of Applied Sciences. They set out to quantify what the cash cycle actually contributes to our societies and economies. They work independently and are responsible for the methodology and the results.
The headline finding from the first phase, conducted in Germany, is striking: the cash cycle contributes around 1.2% of German GDP. This is huge: in real terms, about 54 billion euro per year. Cash supports jobs, businesses, and infrastructure, and it delivers wider benefits in resilience, inclusion, and competition in payments that have so far never appeared in official calculations.
We are now expanding the research to other countries, and are actively inviting central banks to bring the study to their own markets. The feedback we received from central banks is that this is extremely useful data as it gives them the other side of the ledger. If you only ever measure the cost of cash, you can only conclude that it is a cost. Now they can quantify the benefit as well, giving the policymakers the evidence to make properly balanced decisions.
Cash remains a critical part of the global payments ecosystem alongside rapid digitalisation. What role do you see physical currency playing over the next decade, and what are the biggest misconceptions about its future?
Over the next decade I see cash playing multiple roles. It will remain the everyday payment choice for hundreds of millions of people. It will be the guarantee of choice, privacy, inclusion, and competition in a complex payments market. And it will be the resilience layer of the whole system, the one means of payment that always works, when networks, power, or systems fail.
There is also a more fundamental point that is often overlooked. Cash is the only sovereign means of payment we have, the only way to pay that does not depend on foreign companies, networks, or services. And it is the only public money: produced by a public institution, the central bank, for the public. Every other payment method is managed and run for private profit. That distinction will matter more, not less, over the next decade.
The biggest misconception is that a cashless society is inevitable and imminent. It is neither. The transactional share of cash has declined in some markets, but demand for cash remains strong and cash in circulation continues to grow in many countries.
A second misconception is that the shift away from cash is simply driven by convenience. Other payment methods may well be more convenient in some situations, but much of this is manufactured convenience. When banks close branches and ATMs, where do you get cash? And where do businesses deposit their daily takings? When card companies sign exclusive card-only deals, that is not consumer preference at work; it is killing choice. And when we are bombarded daily with advertising from global payment providers, impressions are created and habits are formed.
At the same time, many people are rediscovering cash on their own terms: as a budgeting tool, because it makes money tangible; as a way to pay without sharing the transaction with hundreds of data brokers, feeding a consumer profile that lasts forever; or simply because they prefer a human exchange to another contactless tap.
The future of cash is not a question of technology; it is a question of policy choices, and those choices should preserve freedom of choice in how we pay. Cashless is not a choice!
What is one issue relating to cash and currency that you believe deserves far more attention from issuing authorities and the public than it currently receives?
The silent erosion of the cash infrastructure. Cash works as a network: ATMs, bank branches, cash centres, retailers that accept it, and the companies that produce and distribute it. Each individual closure or refusal seems small, but together they can push the network below critical mass. At that point cash does not disappear because people stopped wanting it; it disappears because using it became too hard and thus other payment methods became more convenient. And once infrastructure is dismantled, rebuilding it is slow and expensive, as several countries have discovered.
This is why the ICA is arguing for legal protection of cash, for rules against unilateral cash exclusion, for national cash resilience plans to ensure it supports us in crises, as are currently reflected in the draft EU Single Currency Package. Authorities need to systematically monitor access and acceptance of cash and act before the decline becomes irreversible. The public need to be aware that keeping cash usable is not about nostalgia; it is maintenance of a critical national infrastructure and of our sovereignty.
The pandemic highlighted the importance of resilient payment infrastructure. What lessons has the currency sector learned about the role of cash during times of crisis and uncertainty?
The pandemic taught us a paradox. Transactional use of cash fell, partly driven by unfounded hygiene fears, yet demand for cash rose sharply. When people feel uncertain, they want cash in their pocket. That is a pattern we have seen in every crisis since, from power outages to cyber incidents and geopolitical tensions.
The sector has drawn two lessons. The first is that cash is the payment system’s contingency: when digital systems fail, and they do fail, cash is what keeps commerce moving. Several governments and central banks now explicitly advise citizens to keep a reserve of cash at home for emergencies, which would have been unthinkable advice from officials a decade ago.
The second lesson is that resilience cannot be improvised in a crisis. The cash cycle only works in an emergency if it has been maintained in normal times. You cannot switch capacity, skills, and infrastructure back on overnight, which is precisely why resilience planning must happen now and people need to be encouraged to use it every now and then.
You have been advocating for cash usage via social media, using current trends and methods to attract a younger audience. How do you think using cash would benefit the younger generation?
Cash gives young people something digital payments deliberately remove: friction, and with it awareness. When you hand over a banknote or a coin, you feel the transaction, and you have less money in your pocket. Research consistently shows people spend more carefully with cash, and young people have worked this out for themselves. Cash budgeting has become a genuine trend on social media, with millions using envelope methods to control their spending. We did not invent that; we amplify it.
Beyond budgeting, cash benefits younger people in ways they increasingly value. It is private, leaving no data trail to be profiled or sold. It carries no hidden charges, unlike digital payment fees that merchants pass on to customers through higher prices. It works without a phone, a battery, or a signal. And it builds financial literacy, because physical money makes abstract concepts concrete. Through Cash Matters we make these arguments where young people are, in their formats and their language, and the message resonates because it is about freedom and control, not nostalgia.
What learnings would you share with countries that are earlier in their transition towards a parallel cash and digital payments future, particularly when it comes to educating younger generations about the value, purpose and practical use of cash?
The first learning is: do not dismantle what you will later need. Countries that let cash infrastructure erode during rapid digitalisation have found themselves legislating, at considerable cost, to restore access and acceptance. It is far cheaper to maintain a parallel system than to rebuild one. Digitalisation should add options, not remove them.
The second is to base policy on evidence, not on momentum. Measure the value of cash as well as its cost, monitor access and acceptance, and listen to what people actually do rather than what forecasts say they will do.
On education, my advice is to start early and to be honest about both systems. Financial education needs to include handling physical money, because it is the most effective way to teach the value of money to children. For older students, teach the real trade-offs: convenience versus privacy, speed versus control, and what happens when systems fail. And speak to young people in their own channels and their own language. Framing cash as freedom, control, and smart budgeting works; framing it as tradition does not.
How do you think central banks around the world can better support cash?
First, central banks need to own and support their own product. I often hear that central banks must be neutral when it comes to payments. I understand that they need to be fair, but neutrality often means doing nothing for cash, while digital payments enjoy the backing of a multi-billion industry that spends heavily to push its products and to lobby for favourable legislation. Neutrality cannot mean being passive. At the Global Currency Forum, an influential central banker spoke about active neutrality: ensuring that all payment methods have equal market access, and that the public payment method receives support from public institutions. In practice, that means treating access to cash and cash acceptance as explicit policy objectives, not as market outcomes to be observed: monitoring both systematically, publishing the data, and intervening when access to cash or the freedom to pay with it comes under threat.
Second, they need to plan for resilience. Every country should have a cash resilience plan that keeps the cash cycle functioning through crises, and the capacity behind it, from production to distribution, maintained in normal times.
Third, they need to ensure genuine parity between cash and digital forms of public money. Cash is the only public money in our pockets today, issued by central banks for the public, while every other way to pay is run for private profit. Where central banks are developing digital currencies, cash should enjoy at least the same legal protection, investment, and promotion. A digital euro, for example, should complement euro cash, not replace it.
Finally, they need to invest in evidence. Central banks are trusted institutions, and their voice carries most weight when it is backed by data. Supporting independent research into the value of cash is active neutrality in practice, and we warmly invite central banks to join the Value of Cash study.
The Global Currency Forum (GCF) takes place every two years to accommodate insightful discussions and collaboration amongst the currency industry. How do you then take these discussions beyond the GCF, and how does it shape future campaigns?
The GCF is where the whole community meets: this year in Antalya we welcomed 430 delegates from more than 60 countries, including 141 from central banks and state printing works. But the forum is the beginning of the work, not the end of it.
The discussions feed directly into what the ICA does for the following two years. The themes and concerns raised at the GCF shape our advocacy priorities, inform our committees, including our work on sustainability and set the agenda for the Cash Matters campaign. We carry the content outward through our newsletters, articles, and thought leadership, so the insights reach well beyond the delegates in the room. GCF also supports the industry as any surplus is reinvested back into industry initiatives.
The two-year rhythm suits this well. It gives us time to act on what the community tells us, and to return to the next forum with results to show, not just topics to discuss.
[Download the interview as it appeared in Going Beyond (PDF)]
Pull quotes for the page layout (from the original): “Authorities need to systematically monitor access and acceptance of cash and act before the decline becomes irreversible.” / “Supporting independent research into the value of cash is active neutrality in practice, and we warmly invite central banks to join the Value of Cash study.”